Conventional loans in California, the flexible classic.
Conventional loans are not government-insured and follow Fannie Mae and Freddie Mac guidelines. They offer flexible terms and, for many borrowers, lower costs over time. See if one may fit your plans.
- Fixed and adjustable-rate options
- Lower down payment programs for qualified buyers
- Primary homes, second homes and investment properties
Not a loan offer or commitment to lend. Available for California properties only. Programs, rates and terms vary and are subject to credit approval and underwriting. See licensing & disclosures.
What a conventional loan may offer.
Conventional loans are the most common mortgage type. Terms depend on your credit, down payment, property and lender.
Who it may fit
- Buyers with good credit and stable income
- Buyers who want the option to drop mortgage insurance later
- Second-home buyers and investors
- Homeowners looking to refinance or tap equity
What to know first
- Credit score and debt-to-income ratio have a bigger effect on pricing than with some government loans.
- Investment and second-home loans usually need a larger down payment.
- Conforming loan limits vary by California county. Above them, a jumbo loan may apply.
- An FHA or VA loan may be a better fit for some borrowers. We compare them with you.
Common conventional loan questions.
What is the minimum down payment for a conventional loan?
Some conventional programs allow as little as 3% down for qualified buyers, while others require 5% or more. Second homes and investment properties typically require more.
What is PMI and can I avoid it?
Private mortgage insurance protects the lender when you put down less than 20%. You can generally avoid it with 20% or more down, and it can typically be removed later once your equity reaches the required level.
Fixed or adjustable rate: which is better?
A fixed rate keeps your principal and interest payment the same for the life of the loan. An adjustable rate starts fixed for a period and then can change. The right choice depends on how long you plan to keep the loan and your comfort with risk.
Does taking the quiz affect my credit?
No. The quiz and calculator do not involve a credit check, and you are not obligated to apply.
Explore other California loan options
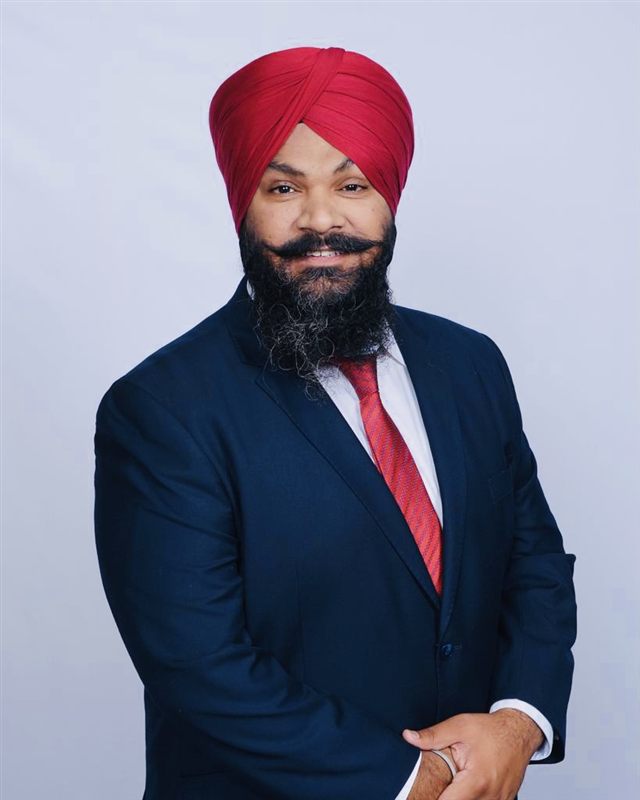
Jagdish Singh
Licensed California real estate broker · Mortgage Loan Originator
I’m a licensed real estate broker working in the California market. I started as a realtor in 2016, earned my broker’s license in 2019, and have helped hundreds of families buy homes with guidance grounded in local market knowledge.
I’m committed to personalized service for clients across the region, and I’m fluent in English, Hindi and Punjabi.
- English
- हिन्दी
- ਪੰਜਾਬੀ
Landstar Realty Group · DRE Broker License #02110817Jagdish Singh · DRE Broker License #02002912Mortgage Loan Originator · NMLS ID #2734008 · with H.O.M.E. Lending, NMLS ID #1786164  Verify on DRE · Verify on NMLS Consumer Access
Ready to see where you stand?
It takes about a minute, and there’s no obligation.
Start the quick quiz